Guide · · 9 min read
Ontario Warehousing: The Backbone of Canadian Distribution
Ontario contains 40% of Canada's population and 50% of its ecommerce demand. Ontario warehousing infrastructure — GTA, Hamilton, London, Ottawa — is the operational backbone of Canadian distribution.
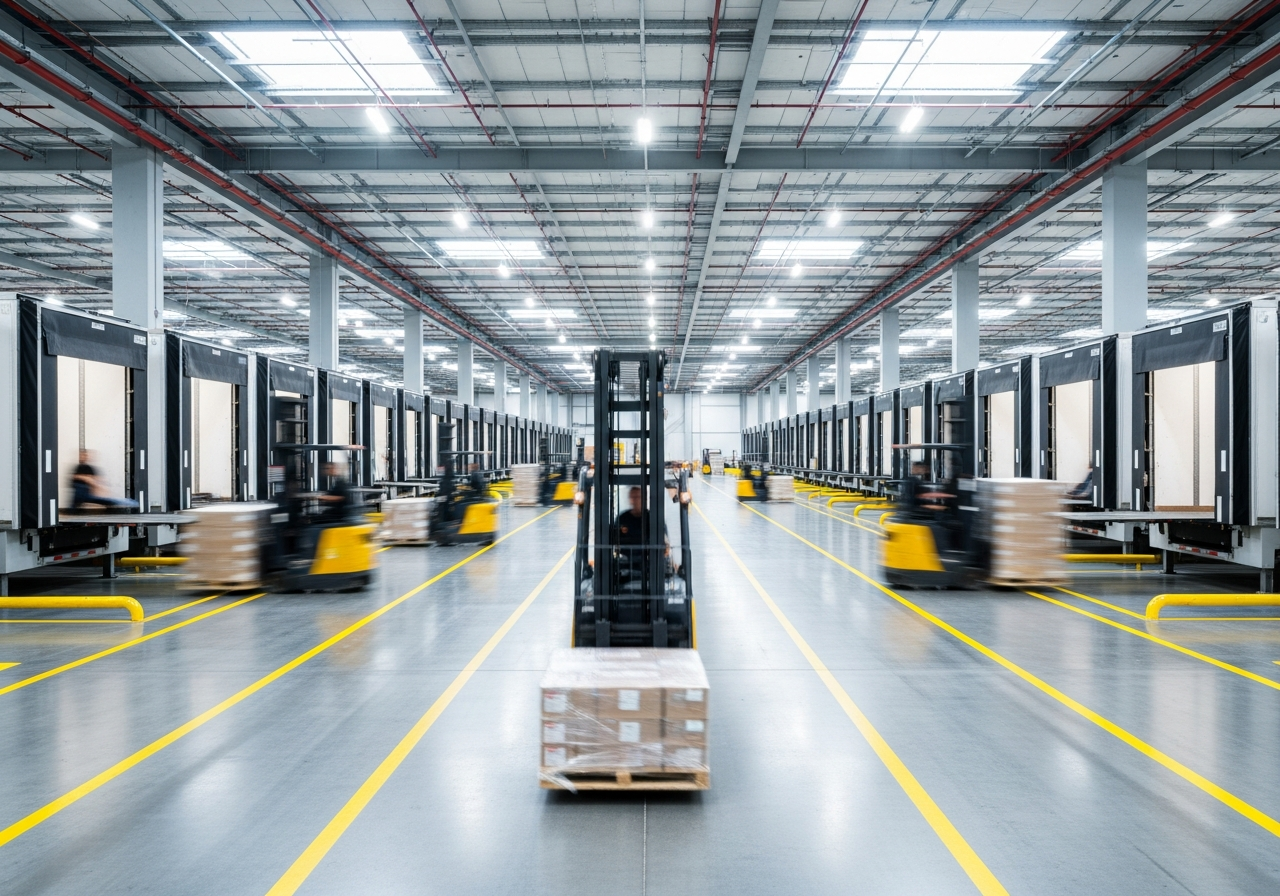
Ontario contains 40% of Canada's population and ~50% of its ecommerce GMV. The province is structurally the backbone of Canadian distribution — every major Canadian retailer, every major DTC brand, and every Canadian-targeting international brand operates fulfillment infrastructure somewhere in Ontario. This guide breaks down provincial market dynamics: GTA dominance, secondary market growth (Hamilton, London, Kitchener-Waterloo), Ottawa's rise, and what brands need to know about Ontario warehousing strategy.
Ontario warehousing market overview
The Greater Toronto Area dominates with roughly 850M sq ft of industrial space — the second-largest industrial market in North America after the Inland Empire/LA. Mississauga, Brampton, Vaughan, and Markham collectively house the bulk of large-tenant 3PL and corporate distribution operations. Secondary Ontario markets — Hamilton, Kitchener-Waterloo, London, Ottawa — collectively add another 200M+ sq ft, with growing tenant demand driven by GTA real estate pressure and population spread.
GTA market dynamics
GTA industrial vacancy has run below 1.5% for most of the past 4 years, pushing net lease rates above $20/sq ft and triggering record warehouse construction. Despite construction activity, demand continues to outpace supply driven by ecommerce growth, near-shoring of manufacturing inventory, and cold chain expansion. The result: GTA warehouse leases remain a seller's market and are likely to stay that way through at least 2027.
- GTA industrial vacancy: <1.5% sustained 2022-2026
- Net lease rates: $20-26/sq ft (Mississauga/Brampton)
- Sub-market price gradient: GTA > Hamilton > KWC > London > Ottawa
- New build delivery: 18-24 month lead times
Secondary market growth
Hamilton, Kitchener-Waterloo, London, and Ottawa are all growing as Ontario warehousing alternatives. Each offers 25-50% lower lease rates than equivalent GTA space, with reasonable transit time tradeoffs: Hamilton next-day to GTA + Niagara; KWC next-day to GTA + Southwestern Ontario; London next-day to GTA + 401 corridor + Windsor cross-border; Ottawa central position covering Quebec-Windsor corridor with US Northeast cross-border bonus. Brand selection of secondary market should match customer geography and cross-border priorities.
Strategic implications for brands
The strategic question is no longer 'should I be in Ontario' (the answer is yes) — it's 'where in Ontario'. GTA-anchor + secondary node has become common for brands above $5M GMV; pure secondary-market anchor (Ottawa, London, Hamilton) makes sense for cost-sensitive operations or for brands with specific geographic tilt; multi-node Ontario only makes sense above ~$25M GMV with diversified customer geography.
Ontario warehousing strategy decisions are typically a 5+ year commitment. Get geographic positioning right at the outset — switching costs are significant.
Frequently Asked Questions
Is GTA fulfillment still the default for Ontario operations?
For brands serving primarily GTA customers, yes. For brands serving national customers, Ottawa increasingly competes successfully on per-unit cost and national transit time.
What's the cost difference between GTA and secondary Ontario markets?
Typically 25-50% lower lease rates in secondary markets (Hamilton, London, Ottawa), with parallel labour cost differentials. Per-unit fulfillment cost typically 10-20% lower in secondary markets.
Can ByExpress operate across multiple Ontario nodes?
Yes — our Mississauga hub serves the GTA and Southwestern Ontario, and our Ottawa hub serves Eastern Ontario, Quebec, and US Northeast cross-border. Unified WMS visibility across both nodes.